
Beyond the cheque: why strategic VC arms are becoming key partners for biotech
Corporate venture capital is no longer a rarity on biotech cap tables. At NLSDays 2026, representatives from pharma, medtech and healthcare investment arms discussed what corporate investors offer beyond money, how they handle shifting strategies, and why two corporate investors can be better than one.
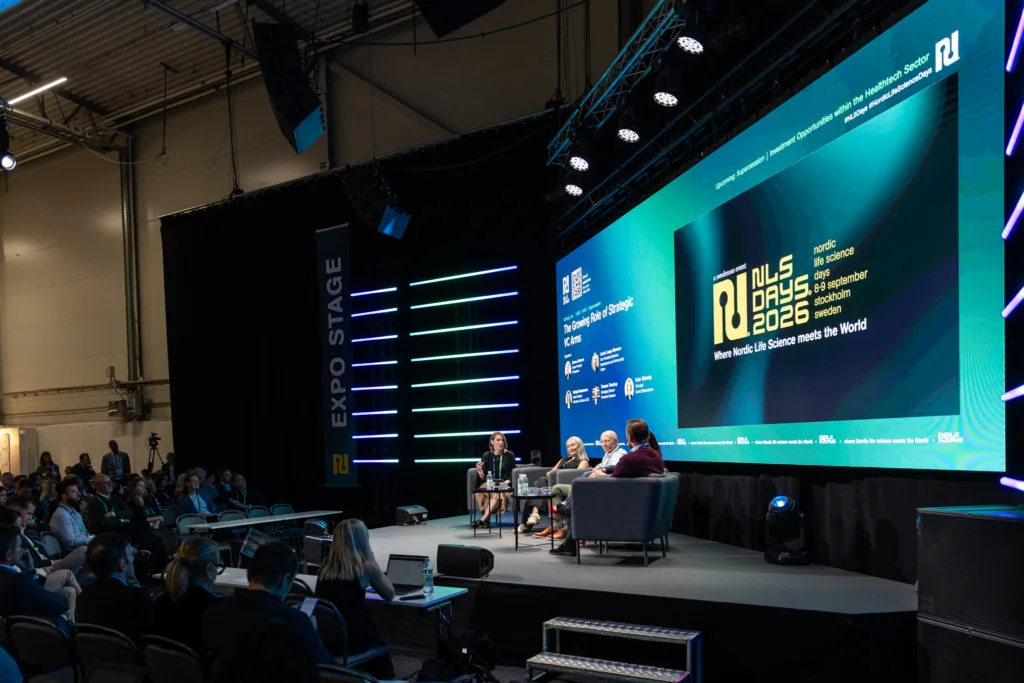
Ester Sklarsky, Principal at Sound Bioventures, moderated the supersession “The Growing Role of Strategic VC Arms”. She opened with figures showing how common corporate investors have become. About 70 percent of biopharma companies that have gone public in the US since 2022 had a corporate investor on their cap table. So did 60 percent of the companies acquired by pharma.
“It’s not a rarity,” Sklarsky said. “But corporate investors tend to get lumped into one group, and they are quite different.”
For Emma Johnson, Senior Principal at M Ventures, venture investing is another pillar of a corporate’s external innovation strategy. “It’s a window into the innovation happening outside the organisation,” she explained. “Both the complementary technologies and the disruptive, potentially threatening ones that a company needs to be aware of.”
Jacob Lange Moresco, Vice President, Business Development and Partnerships at Gubra, described a different model. Gubra does not invest in syndicates but seeks partnerships where the two sides can develop drugs together. “We’ve proven over the years that we can discover and develop drugs, and we’ve done around 15 deals,” he said. “We have so much to offer beyond finances, so we decided not to make purely financial investments.”
Nadiya Ishnazarova, Senior Director at Johnson & Johnson Innovation (JJDC), encouraged founders to check her claims with JJDC’s portfolio companies. Having pharma at the table, she said, means having a potential buyer who can help define what the product and data package should look like. It also means access to expertise in CMC, regulatory questions and clinical trials. “Even very specific things, like which CROs we have worked well with if you want to run a trial in China,” she said.
“If you’re considering a CVC for your cap table, go and talk to your peers. Hopefully they will support my positive outlook.”
JJDC often takes a board or observer seat and brings in colleagues from R&D as early as the due diligence stage. “When scientists already know each other, it’s a much easier and more trusting discussion to have,” Ishnazarova said.
Thomas Thestrup, Managing Director at Fresenius Ventures, pointed to an advantage that even pharma lacks. “Pharma typically stops at the point of sale,” he said. “We actually have the doctors who provide the drugs and treat the patients, with daily interactions with them.” That gives the new fund a unique platform to scale technologies, although partnerships are never forced.
Asked how corporate investors avoid being too conservative, Ishnazarova laughed. Managing internal stakeholders is “80 percent of our job”, she said. “If we bring a target that internal teams have worked on for 25 years without cracking it, everybody thinks they’re the smartest people in the room.” Part of the job is explaining why external teams may succeed where the company has not, and that sharing risk with other investors is itself valuable.
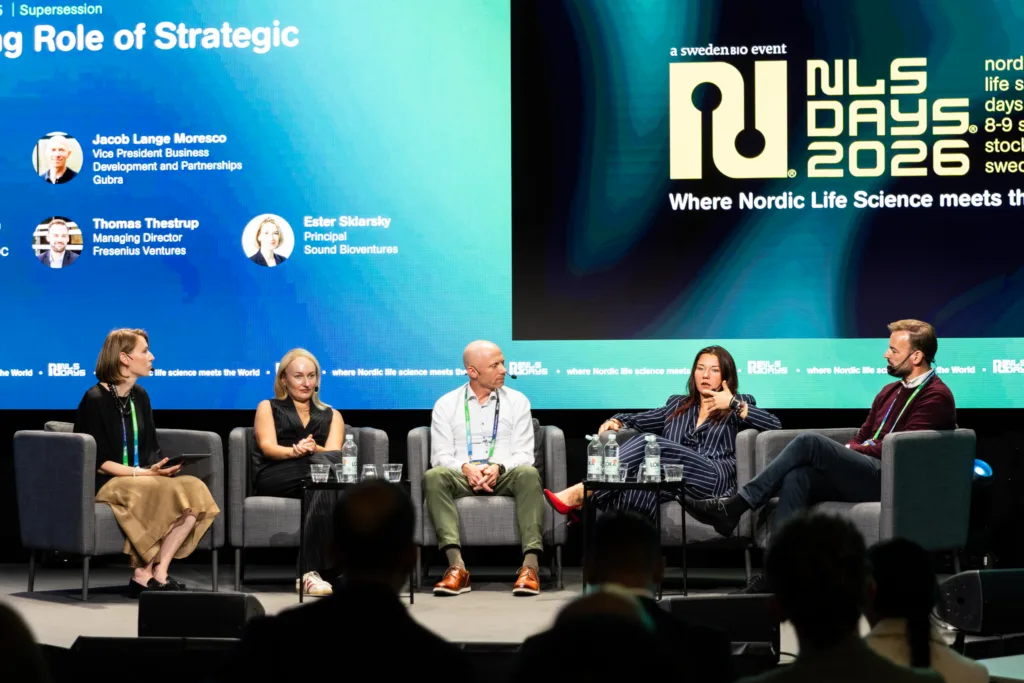
Thestrup said that “innovation” was once almost a forbidden word at Fresenius, though that has changed under new management and a new strategy. Johnson, who joined M Ventures this year, described the challenge of reframing internal scepticism: “Experts are quick to point out where the data gaps are. But this financing is about generating that data, and that is the value we can create together.”
Sklarsky raised a common founder fear: what happens if the parent company changes strategy? Both Johnson and Ishnazarova said their funds have a dual mandate. Strategic fit matters at the first investment, but after that they act as financial investors. “If the strategy changes, we take off the strategic hat and assess the opportunity on a purely financial basis,” Ishnazarova said. Internal champions often stay supportive even when the area is no longer a priority.
“We know reputation matters, so we’re not trying to leave companies high and dry.”
Thestrup added that a fund should never invest if its own parent is the only plausible buyer. Since Fresenius Ventures is moving into new areas, the risk of deprioritisation is smaller. “We are trying to create M&A optionality,” he said.
None of the panellists typically ask for rights of first refusal. Johnson said such terms belong in business development discussions, not venture deals. Ishnazarova noted that they are more common in medtech, where the pool of buyers is smaller. In biotech, corporates usually invest as “vanilla” equity investors, although creative structures have appeared in a tough funding climate. Thestrup warned that option deals can backfire: “If a strategic walks away, the company can be scarred, not because of bad data but because it carries that weight.”
Johnson cited Endpoints’ 2026 list of the 100 most active biotech investors, where 12 were corporate investors. Ishnazarova traced the trend back to 2022–2023, when many funds struggled to raise capital and kept their cash for their own portfolio companies. With balance-sheet or evergreen structures, corporate investors stepped in. “All of a sudden, CVCs became the saviours,” she said. “Now we’re invited to almost every round.”
She argued that two corporate investors are better than one. One of her portfolio companies has five in the boardroom. Strict conflict-of-interest rules decide when each must leave the room during a transaction. As Ishnazarova put it, if several pharmas are around the table and all are interested, “they’re bidding for you”.